Catching Up on Some Items

I feel so behind on so many items. I guess that’s normal when you return from a vacation…and you look at your calendar and realize that you’re heading out of town again in just a week for your annual continuing education seminar.

Back in April the proprietor of Tax Fool sent me an email right at the end of tax season. I’ve finally gotten around to looking at his site, and it’s another site that debunks tax protester myths. I’m adding it to my links (on the right).

Roni Deutsch also has a tax blog worth reading. I’m linking it, too. I’m removing a link to a blog that hasn’t been updated in a long time (and I presume is dead).

And as hard as it is for me to believe, in less than a month the second quarter estimated tax payment is due. Time just keeps on moving….

Posted in Taxable Talk | Comments Off on Catching Up on Some Items

Is an Adult Entertainment Tax Next for California?

As California continues looking at a massive budget deficit (somewhere between $8 billion and $20 billion) some in the state legislature are looking to implement a tax on the Adult Entertainment Industry. A 25% tax on film production, strip, er, adult entertainment clubs, and pornographic videos.

Larry Kaplan, head of the California Branch of the Association of Club Executives, said that this proposed legislation would “…devastate the San Fernando Valley…[I]t would take $3.5 billion out of California.” Matt Grey, a lobbyist for the Adult Entertainment Film Industry, told Reuters that it’s cheaper to fly performers to Bucharest, Romania than to drive them to the Valley.

Meanwhile, Republicans are still promising to block all tax increases so it’s likely that this porn tax is doa.

Posted in California | Comments Off on Is an Adult Entertainment Tax Next for California?

Sales Tax on Hot Chocolate

One of my favorite weekly reads is the Leonard Letter. Bill Leonard is one of the elected members of the Board of Equalization. Mr. Leonard notes,

“Late last year an article entitled “Why Is Buying Hot Chocolate So Confusing?”appeared in a tax journal. It was bandied about as an example of how difficult it is for California retailers to comply with the state’s sales tax law. I asked the Board of Equalization staff to respond to the article and have now reviewed a 3 ½ page letter attempting to explain when hot chocolate is taxable. That it takes 3 ½ pages to answer what should be a simple yes-or-no question gives you a window into the absurdity that is state tax law.”

The letter that Mr. Leonard references is here. The question arises as sales tax was collected on hot chocolate sold at a Starbucks inside a Target store but not inside a Safeway (grocery) store nor in the lobby of the Bank of America building in downtown San Francisco. From the letter:

“Sales and Use Tax Regulation 1602, Food Products, (copy enclosed), provides that generally tax does not apply to sales of food products for human consumption except as provided in Regulation 1503, 1574 and 1603. “Food products” include among other items, coffee, tea, noncarbonated and nonalcoholic beverages, breads, bakery products, pizzas, candy, confectionery, chewing gum and cookies. Generally, tax does not apply to sales of the above items except when they are sold under circumstances as provided in Regulations 1503, 1574 and 1603.”

After nearly three pages of legalese the author of the letter notes, “Based on the information presented in the article, it is not clear why sales tax was collected by Starbucks on the sale of the hot chocolate.”

And some legislators want to extend sales tax to services. Oh, joy….

Posted in California, Sales Tax | Comments Off on Sales Tax on Hot Chocolate

Vallejo Bankrupt

The city of Vallejo, in Northern California, will declare bankruptcy sometime in the next few days. Why?

Vallejo has a declining industrial base. That’s not a surprise—all of California has that problem. Companies that can move do (or don’t add to their existing facilities in California).

Vallejo had a huge employer—the Navy. However, the Navy left Vallejo several years ago and no one replaced them.

Vallejo (and many other cities in California) have huge labor costs for public employees. The public employee unions wouldn’t accept the cuts that the city asked. It’s certain that during bankruptcy that the city will ask for the contracts to abrogated.

Is Vallejo a harbinger of what impacts all of California? For some cities, perhaps. Cities in California that are dependent on a single employer, and have high fixed costs need to be watchful. It will be interesting how this plays out with the background of California’s huge budget deficit playing out.

Posted in California | Comments Off on Vallejo Bankrupt

Heading to Chicago

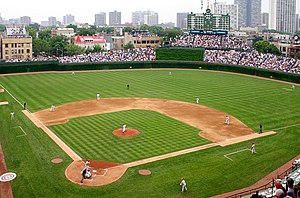
I’m heading to Chicago for the next week, including Friday’s game at Wrigley Field. I’ll apparently need my long-sleeve shirts as the temperature is supposed to drop 30 F over the next two days.

In any case, posting will be light while I’m in Chicago visiting friends and family.

Posted in Taxable Talk | Comments Off on Heading to Chicago

Snipes Files Notice of Appeal

As promised, Wesley Snipes’ attorneys have filed a notice that they intend to appeal Snipes’ conviction and sentencing to the 11th Circuit Court of Appeals. The notice doesn’t specify what arguments they plan on using. The actual appeal will be filed later this year.

Posted in Tax Evasion | Tagged | Comments Off on Snipes Files Notice of Appeal

LA Times: Let’s Tax Our Way Out

The Los Angeles Times today editorializes that the way for California to escape the budget crisis is to tax services: “Lawmakers cannot act in a fit of panic, but the scope of this year’s challenge should encourage new solutions, including service taxes.”

On the contrary, instead of looking for new taxes California should really look outside of the box and cut or eliminate current taxes. I can just imagine the Times reading this and thinking I’m nuts. I’m not.

California has spent itself into this problem; we’re going to have to drastically cut spending. Some state employees are going to lose their jobs but they really should never have been hired in the first place.

What will happen if the state imposes a service tax? It will cost small employers–more bureaucratic paperwork to deal with. I’ll have to increase my fees to cover the costs. That will lead to fewer sales–if price increases and demand is steady, the quantity sold will drop (basic economics). The amount of money raised by the new service tax will be less than what will be projected.

As of today Republican leaders in the State Legislature are holding firm on no new taxes. It figures to be a long summer of the press and Democrats (and possibly the Governator) asking for new taxes and Republicans shooting those proposals down. At least I hope that’s the scenario that plays out.

Posted in California | Comments Off on LA Times: Let’s Tax Our Way Out

Loss of Income Insurance Leads to Evasion

Buddy’s Carpet & Flooring is a Cincinnati-based chain of carpet stores. Its owners in the late 1990s devised a method of saving on their taxes—they purchased eight “loss of income” life insurance policies for $3.6 million. Those policies led to tax savings of around $700,000 in 1998 and 1999.

There’s only one problem: the policies were shams according to the IRS. The then owners were refunded 81% of the premiums. The IRS prosecuted the two owners (Leif Rozen and Burton “Buddy” Kallick) and the company’s in-house counsel (Alan Koehler). Mr. Kallick died in January 2007 before the case came to trial.

Last week a jury agreed with the government’s view that the policies were a sham. Mr. Rozen was found guilty of conspiracy and tax evasion while Mr. Koehler was found guilty of filing a false tax return. Earlier, Milton Liss and Bruce Cohen, who were insurance salesmen, were found guilty of conspiracy to defraud the United States. All are now awaiting sentencing and will likely be spending some time at ClubFed.

News Stories: Cincinnati Enquirer, Business Courier of Cincinnati

Posted in Tax Fraud | Comments Off on Loss of Income Insurance Leads to Evasion

One CA LLC Fee Case Resolved; Two to Go

The Franchise Tax Board will now begin to send out some refunds on LLC Fees paid. These fees have been challenged in three court cases. Two of these cases are still in litigation. The one case that’s been resolved is Northwest Energetic Services (NES), LLC v. Franchise Tax Board.

The NES case related specifically to a foreign (out-of-state) LLC that had registered in California with the Secretary of State but had no business in California. If you’ve filed a claim with the FTB and the FTB can determine that the LLC meets the NES criteria, then the refund(s) will be issued.

However, if the FTB can’t determine whether an LLC meets the NES criteria no refund will be issued. So if your LLC or your client’s LLC meets that criteria, then you should send the FTB the following:

* The LLC’s name, address, and the name and phone number of the managing member or designated contact person.
* The LLC’s Secretary of State file number or Franchise Tax Board temporary LLC number (for unregistered entities), and Federal Employer Identification Number.
* Taxable Year(s) involved.
* A statement that the LLC did no business in California for each of the taxable years for which the claim is being filed.

If your client hasn’t filed a claim for refund but wants to, include the above information in a letter along with the statement, “This letter constitutes a claim for refund for (taxpayer’s name) – No income attributable to California,” and the amount of claim per year. Any claim for refund must be signed by a representative with power of attorney (POA) or signed by the LLC’s managing partner.

You can fax the information to the FTB at 916.845.9796. You can also mail the information to the FTB to:

ABS 389 MS: F340
Franchise Tax Board
PO Box 942867
Sacramento, CA 94267-8888

If you use FedEx or another private courier, then send it to:

ABS 389 MS: F340
Franchise Tax Board
C/O FTB Notice 2008-2
9465 Butterfield Way
Sacramento, CA 95827

The FTB has issued a notice here.
Posted in California | Comments Off on One CA LLC Fee Case Resolved; Two to Go

The List

The Franchise Tax Board has posted its six month revision of its 250 biggest scofflaws. The largest debtors from October are gone, and a new name leads the list: Pinehill Investment of Rye, New York owes the FTB $6.133 million. The largest individual debt is Michael S. Fitzsimmons of New York City; according to the FTB his debt is $4.436 million.

There is still at least one celebrity on that list. Orenthal Simpson probably has more to worry about than his $1.528 million debt.

It took $195,994.96 to make the list. And five taxpayers have paid in full (collecting $604,395.31 to California). Others are obviously on payment plans or in negotiations as the top tax delinquent is no longer on the list. What we don’t know is whether or not these taxpayers were shamed into paying or just happened to get around to it.

Posted in California | Comments Off on The List
